Saudi Arabia’s shift beyond hydrocarbons is built on the idea that non-oil activity can steady the economy when oil weakens. Academic work on Saudi diversification describes a state-dependent pattern: oil tends to act as a growth accelerator during expansions, while the non-oil sector helps stabilise the economy during downturns. That stabilising role is central to Vision 2030’s emphasis on structural transformation and resilience. Yet the same research also frames why volatility matters: oil prices and demand can swing, and oil is a non-renewable resource. The diversification promise, in other words, is not only about new industries, but about lowering exposure to shocks.
In 2026, the stress test has not been confined to oil infrastructure. Reports on the escalation describe operations extending into the Saudi interior and targeting a mix of facilities, including airports and other sites in Riyadh. The declared targets on November 7 included King Khalid International Airport, oil tanks and a distillation tower linked to Aramco in Riyadh, Aramco in Khurais, and pumping station No. 8 in Dawadmi, along with military gatherings in several locations. The next day’s reported operations again listed King Khalid International Airport, Aramco tanks, a financial center in Riyadh, and Aramco in Abqaiq. This broader target set is why Saudi non-oil economy Houthi risk has become a practical question, not just a geopolitical headline.
Non-Oil Sectors Became Front-Line Exposure
Economic data cited alongside the escalation underlines the pressure. Preliminary figures referenced from the Saudi General Authority for Statistics (GASTAT) show GDP contracting 3.8% year-on-year in the third quarter of 2026, marking a second consecutive quarterly contraction. Within that, oil activities fell 20.4% after a 24.8% decline in the second quarter, while non-oil activities grew 1.9%. Another account using GASTAT’s flash estimate says non-oil activity grew just 0.6% in the second quarter of 2026. The same reporting argues the war disrupted logistics networks, transport, and the events calendar that diversification programs rely on, including cancellations and deferrals as security concerns rose.
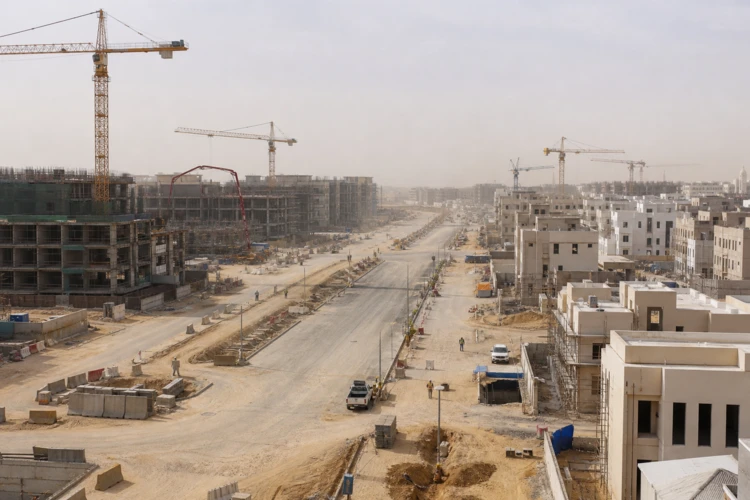
Those vulnerabilities matter because diversification plans explicitly lean on sectors that need predictable mobility and connectivity. Vision 2030-focused analysis describes a portfolio spanning tourism, mining, technology, defense, entertainment, financial services, manufacturing, and logistics, with institutional support and regulatory frameworks to accelerate growth. A separate Saudi diversification overview notes sector-specific regulators in areas such as media, tourism, entertainment, data and artificial intelligence, and industrial development, plus special economic zones including KAEC, Ras Al-Khair, Jazan, and a Cloud Computing SEZ at KACST. These are designed as “testbeds” for liberalised rules. But when airline routes are cut and travel advisories proliferate, the non-oil mix most visible to outsiders—tourism and events—can be directly disrupted.
The strategic question is whether the non-oil base can be resilient in the same security environment the oil economy requires. One Vision 2030 analysis sets an ambition for non-oil GDP to represent about 55.6% of total GDP by 2030, framing it as a compositional shift driven by faster growth in new sectors. Another notes Saudi Arabia’s total GDP at $1.27 trillion and describes this as 53% of total GCC output, arguing the trajectory matters regionally. Yet it also warns that the “quality” of diversification counts, distinguishing between government-funded activity and genuinely competitive tradable sectors. The 2026 disruption shows why that distinction matters: non-oil growth can exist, but still be sensitive to corridor closures, transport disruption, and the security premium that shapes investment decisions.
Why are attacks on airports and logistics a diversification problem for Saudi Arabia?
What did GASTAT-linked figures show about oil vs non-oil performance in 2026?
How does research describe the stabilising role of the non-oil sector in Saudi Arabia?
What is meant by Saudi non-oil economy Houthi risk in 2026?